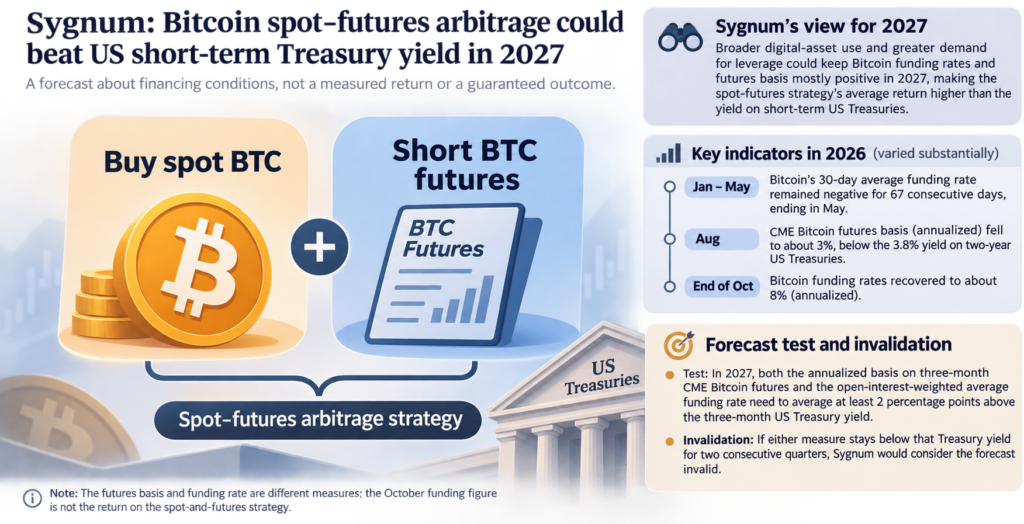
As reported on November 19, 2026, Sygnum forecast that a strategy buying spot Bitcoin while shorting Bitcoin futures could earn an average return above the yield on short-term US Treasuries in 2027. This is a forecast about financing conditions, not a measured return or a guaranteed outcome.
The relevant indicators had varied substantially in 2026. Bitcoin’s 30-day average funding rate remained negative for 67 consecutive days, a stretch that ended in May. According to Sygnum’s report, the annualized CME Bitcoin futures basis fell to about 3% in August, below the 3.8% yield on two-year US Treasuries. By the end of October, Bitcoin funding rates had recovered to an annualized level of about 8%. The futures basis and funding rate are different measures; the October funding figure should not be read as the return on the spot-and-futures strategy.
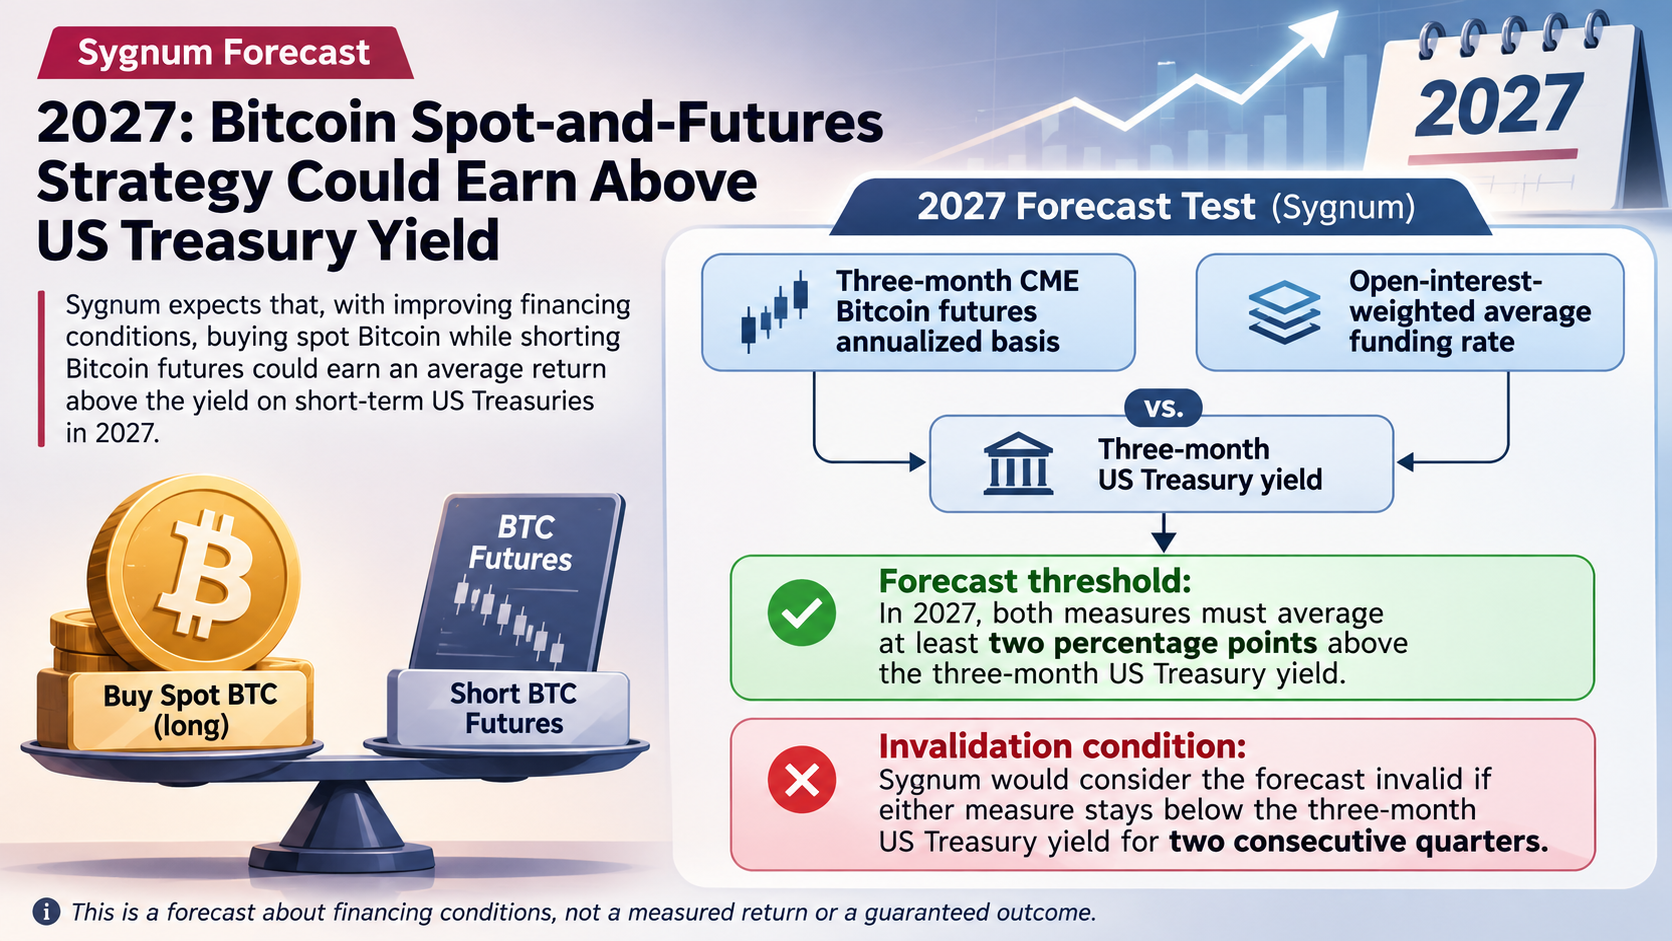
Sygnum expects broader digital-asset use and greater demand for leverage to keep funding rates and futures basis mostly positive in 2027. It also set a test for its forecast: both the annualized basis on three-month CME Bitcoin futures and the open-interest-weighted average funding rate would need to average at least two percentage points above the three-month US Treasury yield during 2027. Sygnum said it would consider the forecast invalid if either measure stayed below that Treasury yield for two consecutive quarters.